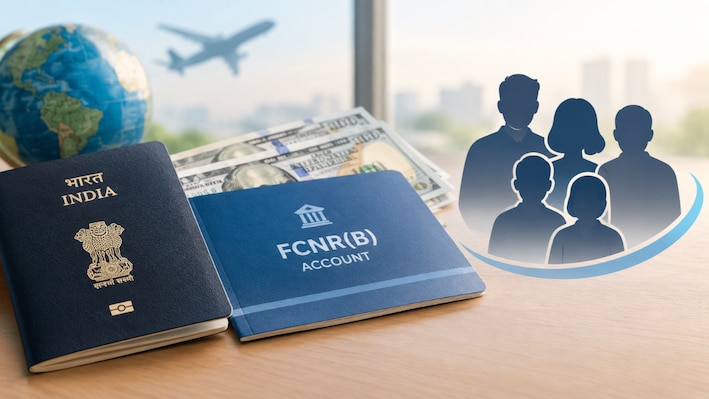

New Delhi: The Non-Resident Indians and the Overseas Citizens of India (OCIs) who want to park their foreign currency savings in India have the provision of Foreign Currency Non-Resident Bank or FCNR(B). Moreover, they may choose to add a family member who is an Indian resident as a joint account holder.
Adding a family member who is an Indian would help in managing the account more efficiently.
A person is allowed to open a joint FCNR(B) account with an Indian relative, however conditions may apply. Therefore, before opening such an account one should go through the details regarding with whom it can be operated and which mode of operation is applicable.
Non-Resident Indians (NRIs) and People of Indian Origin (PIOs) can open a joint FCNR(B) account with a resident relative on a 'Former or Survivor' basis only, which means the secondary account holder is allowed to use and manage the account only after the death of the former member.
It is important to note that the NRI/PIO/OCI must be the primary holder of the joint account.
Only one resident Indian can be the joint account holder. If the account is operated with NRIs, a maximum of four members are allowed to be joint holders. In that case, the mode of operation would be 'either or survivor'. This mode allows all the parties to manage the account independently.
The State Bank of India (SBI) website states, "Funds deposited in the account can be by way of fresh remittance from overseas or transfer from other NRE / FCNR (B) account or NRO account (subject to limit)."
The following individuals are eligible as relatives to hold the FCNR(B) account jointly:
-- Members of a Hindu Undivided Family
-- Husband and wife
-- The relation between the two should be either as follows:
a) Father (including step-father)
b) Mother (including step-mother)
c) Son (including step-son)
d) Son's wife
e) Daughter
f) Daughter's husband
g) Brother (including step-brother)
h) Sister (including step-sister)
The account holders are allowed to fund the deposits in two ways: through foreign currency remittance from overseas and through another FCNR(B) or Non-Resident (External) account.
A Non-Resident (External) account converts the foreign currency into Indian currency based on the existing exchange rates to park the savings in India, whereas an FCNR(B) maintains the deposit in the foreign currency.
An FCNR(B) deposit comes with certain benefits, including tax exemption and repatriation. The total amount deposited in the FCNR(B) account, including the principal and the interest, is exempt from Income Tax in India. Moreover, the total amount in the fund can be transferred outside India fully and freely.
Stay informed on all the latest news, real-time breaking news updates, and follow all the important headlines in india news and world news on Zee News.