
• हिन्दीEnglishमराठीবাংলাதமிழ்മലയാളംગુજરાતીతెలుగుಕನ್ನಡଓଡ଼ିଶାZ BharatPHHBusinessWION
  • facebookyoutubetwitterwhatsapp
Zee News Hindi
  • news
  • Live Blog
  • photos
Add Zee Business As A Preferred Source
App
  • Live TV
  • Latest News
  • India
  • World
  • Entertainment
  • Sports
  • Business
  • Lifestyle
  • Astrology
  • Auto
  • Education
  • Technology
  • News
  • /Business
  • /ITR filing after retirement: Which income is taxable and what exemptions apply?

ITR filing after retirement: Which income is taxable and what exemptions apply?

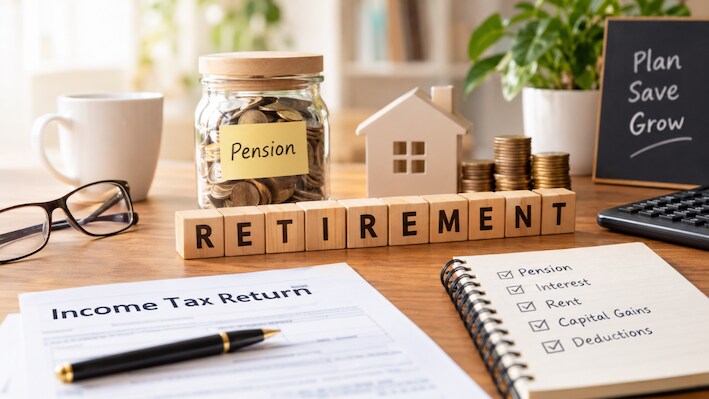
When a person files an Income Tax Return (ITR) after retirement, the total income must be calculated with caution. This can be done by dividing it into three categories: recurring taxable income, one-time retirement benefits that may be fully or partly exempt, and investment income earned after retirement.

Written BySandal Khan
Published: Oct 18, 2026, 06:58 PM IST|Updated: Oct 18, 2026, 07:00 PM IST
joinshare
ITR filing after retirement: Which income is taxable and what exemptions apply?

About the Author

Sandal Khan

Sandal Khan

Sandal Khan is a sub-editor on the business team at Zee Media. She started her media journey in 2025 before joining Zee to pursue a career in business journalism. Having completed her bachelor’s degree in German and a master’s in mass communication from Aligarh Muslim University, she has always been fascinated by the power of words and the role language plays in informing the public and building the right narrative.  Beyond business, her interests include entertainment, culture, history, and geopolitics. An occasional reader, she almost always picks up books by Japanese authors.  She can be reached at Sandal.Khan@India.com 
Read More

Trending

  • News
  • Photos
'Don't know what cricket he was playing': Abhishek Sharma reacts to Yuvraj Singh's playful dig after 113-run carnage

'Don't know what cricket he was playing': Abhishek Sharma reacts to Yuvraj Singh's playful dig after 113-run carnage

2

Hockey Asian Champions Trophy 2026: India make dominating start to title defence with 13-0 win over Bangladesh

3

Commonwealth Kabaddi Championship 2026: Indian men storm into semifinals with 48-20 win over Tanzania

4

AI bubble warning: Microsoft swings axe on 60,000 jobs as sector losses mount

5

IPL 2027: Zaheer Khan set for crucial meeting with MS Dhoni before CSK retention deadline

logo
  • contact us
  • privacy policy
  • legal
  • investor info
  • advertise with us
© 1998-2026 Indiadotcom Digital Private Limited, All Rights Reserved.

New Delhi: Once a person enters the retirement phase, pension replaces salary as the constant source of income. Therefore, retirees often mistake the end of their working life for the end of their tax liability. However, taxes are not payable merely on salaries; rather, income from any source may be subject to income tax.

Even after a person stops working, multiple sources could generate income, such as rental properties, pensions, FD interest, capital gains, etc.

When a person files an Income Tax Return (ITR) after retirement, the total income must be calculated with caution. This can be done by dividing it into three categories: recurring taxable income, one-time retirement benefits that may be fully or partly exempt, and investment income earned after retirement. Check all applicable tax exemptions and deductions carefully, depending on the tax regime. This way, a person can file taxes more efficiently and avoid incurring a penalty.

Taxable income includes:

Uncommuted pension: Though a standard deduction may be available depending on the tax regime chosen, the monthly pension income is taxable.

Pension, annuity, and dividends: Income received as a pension or annuity from insurance companies, as well as dividend income, is taxable. Interest received from cumulative fixed deposits, interest on income tax refunds, income from part-time gigs, and gains from switching or redeeming mutual funds are also taxable.

Interest earned: Interest earned on FDs, RDs, savings accounts, post-office deposits, and Senior Citizens' Savings Scheme (SCSS) accounts is taxable. The old tax regime offers deductions of up to Rs 50,000 under Section 80TTB of the Income-tax Act, 1961 (applicable to returns for FY 2025-26); the new tax regime, however, does not provide such deductions.

Capital gains: Depending on the type of asset and the period of holding, tax may be applicable on gains from the sale of listed shares, mutual funds, immovable property, gold, and other capital assets. The Annual Information Statement keeps a record of transactions reported by banks and other financial institutions. Therefore, figures must be filled in carefully, including those related to switching schemes or redeeming mutual funds.

Rent: Income from residential and commercial properties let out on rent is taxable, with a 30 per cent deduction available for the applicable rental income. Deductions can also be claimed on home loan interest wherever applicable.

A person with zero tax liability may fill Form 121 (which replaced Forms 15G and 15H from April 1, 2026, under the Income-tax Act, 2025) to avoid Tax Deducted at Source (TDS) on FDs and other applicable sources of income.

Income up to Rs 5 lakh per annum under the old tax regime and Rs 12 lakh per annum under the new tax regime has nil tax liability. Gratuity of up to Rs 20 lakh is exempt from tax for non-government employees. For central or state government employees, the full amount is usually exempt from tax.

Retirees should ensure that they avoid any mismatch between the information filed in the ITR and that reported by financial institutions. Documents related to pensions, bank accounts, and capital gains should also be kept together and checked regularly. For retirees, it is important to know the applicable exemptions, required documents, tax rebates, and taxable investments to avoid discrepancies.

Stay informed on all the latest news, real-time breaking news updates, and follow all the important headlines in india news and world news on Zee News.

Add Zee News as a Preferred Source
TAGS:
Income tax